Facing any issue ? Contact us at
0124-6987700
Facing any issue ? Contact us at 0124-6987700
Facing any issue ? Contact us at
0124-6987700
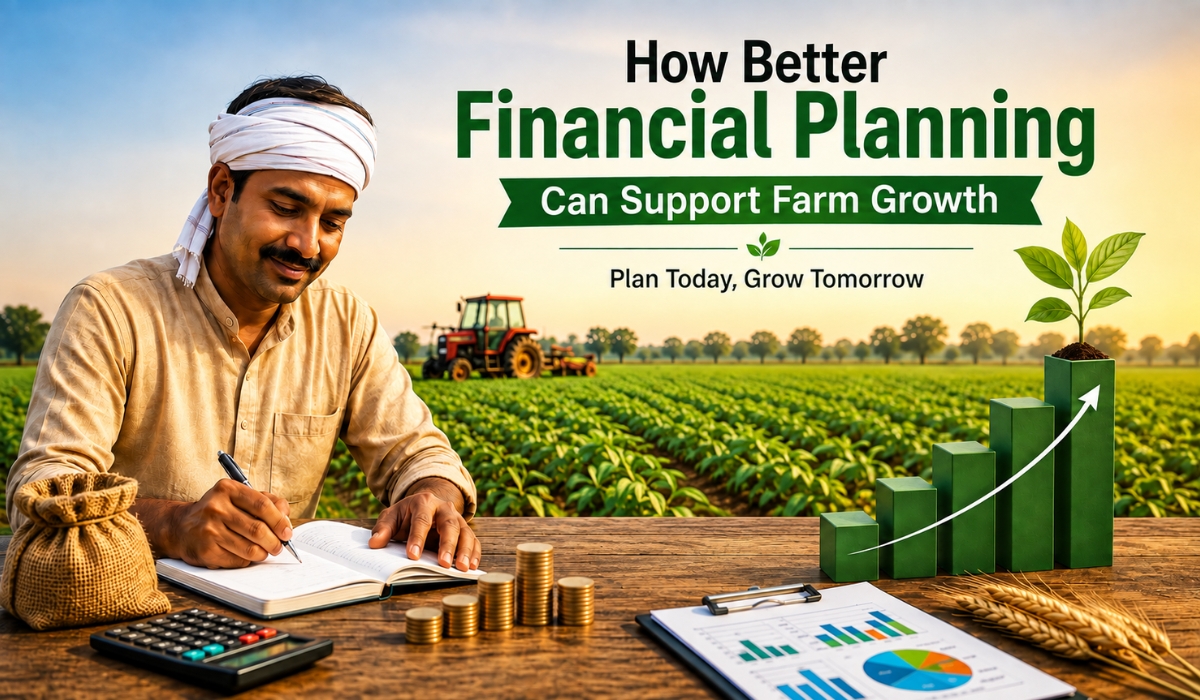
Growing a farm is about more than producing a good harvest. It is also about making the right decisions about where and when to spend, save, and invest. Whether it is buying seeds and fertilisers, repairing or purchasing farm equipment, managing labour costs, or planning for the next season, every financial decision can make a difference.
Farmers often have to manage changing costs, seasonal income, unexpected expenses, and uncertain market conditions. Effective farm financial management can make it easier to handle these challenges and prepare for future needs. With better planning, farmers can use their available resources wisely, make important investments at the right time, and take steady steps towards growing their farm.
Financial planning for a farm involves organising income, expenses, savings, debt, investments, and future financial goals.
It gives farmers a clearer idea of how much money the farm generates, where that money is being spent, and how much can reasonably be invested back into the business.
A practical farm financial plan may include:
The aim is not just to reduce expenses, but to help make better use of the resources available.
Farming often requires spending money well before the income from the crop or livestock is received. Farmers may need to pay for seeds, fertilisers, fuel, labour, irrigation, machinery, or animal feed at different stages of the season.
This is why planning finances in advance can be helpful. It allows farmers to understand the upcoming expenses, manage money through the season, and be better prepared for unexpected costs. It can also help plan for the next crop cycle or make important investments in the farm without putting unnecessary pressure on finances.
Better financial planning can support farm growth in several practical ways.
Knowing exactly where money is being spent can reveal areas where costs are higher than expected.
Farmers can compare spending across different seasons and categories, such as fuel, fertiliser, feed, labour, repairs, and transportation.
This does not mean cutting every expense. Some spending directly contributes to productivity. The aim is to understand which expenses add value and which may require closer monitoring.
Cash flow is particularly important in farming because income and expenses are often separated by months.
A cash-flow forecast can show when large expenses are expected and when farm income is likely to arrive. This gives farmers more time to prepare for periods when available cash may be lower.
Good cash-flow management can also reduce the need to make rushed financial decisions during difficult periods.
New machinery can improve productivity, reduce manual work, or lower certain operating costs. However, purchasing equipment is a significant financial decision.
Before making the purchase, farmers can consider:
This helps farmers determine whether an equipment purchase supports the farm's actual needs and financial capacity.
Loans can provide useful funding for land, machinery, livestock, buildings, irrigation systems, and other farm requirements.
However, borrowing should be considered alongside expected income and repayment obligations.
A financial plan can help farmers see how loan repayments may affect their seasonal cash flow and assess existing debt before taking on new financial obligations.
Unexpected expenses are part of running a farm.
A machinery breakdown, poor harvest, livestock issue, sudden rise in input costs, or change in market conditions can affect the financial position of a farming business.
Maintaining an appropriate emergency reserve can give farmers greater flexibility when unexpected costs arise.
The amount needed will vary from one farm to another, but building a reserve gradually can be an important part of long-term financial planning.
Farm expansion should be based on more than the desire to increase production.
Before expanding, farmers should look at the expected costs and potential returns. This may include additional land, labour, machinery, storage, inputs, transportation, and financing.
It is also worth considering whether there will be enough market demand for the additional production.
A simple expansion plan can answer questions such as:
Answering these questions before investing can help farmers approach expansion more carefully.
Accurate records are the foundation of useful financial planning.
Farmers who regularly record income and expenses have better information when reviewing profitability or planning future investments.
Useful records may include sales, purchases, labour costs, machinery expenses, loan repayments, input costs, maintenance, and other operating expenses.
Over time, these records can reveal patterns that may not be obvious from individual transactions.
For example, a farmer may discover that a particular activity consistently generates higher costs than expected or that certain months require significantly more working capital.
Keeping farm and personal finances separate can make financial management much clearer.
Separate accounts and organised records allow farmers to see the actual performance of the agricultural business without personal spending affecting the figures.
This can make it easier to prepare budgets, review profitability, monitor cash flow, and determine how much money can be reinvested into the farm.
It also creates a clearer financial record when discussing funding or other business decisions with professional advisers.
Monthly or quarterly reviews can help farmers compare actual income and expenses with their original expectations.
If fertiliser prices rise, crop yields change, equipment requires an unexpected repair, or sales are lower than anticipated, the financial plan can be adjusted accordingly.
Regular reviews make the plan a working management tool rather than a document that sits unused.
Growing a farm often requires investment in tractors, agricultural machinery, implements, or other essential assets. IFFCO Kisan Finance offers financing solutions designed to support farmers with these important purchases. Depending on eligibility and requirements, farmers can explore options for new and used tractors, combine harvesters, agricultural implements, and other financing needs.
Having the right financial support can make it easier to plan a major purchase without putting unnecessary pressure on available working capital. Before choosing a financing option, consider the repayment terms, applicable charges, and your expected cash flow. With thoughtful planning, financing can become part of a practical strategy for supporting long-term farm growth.
A successful farm needs more than good production. It needs financial stability that allows the business to respond to challenges and take advantage of appropriate opportunities.
Better financial planning can help farmers manage everyday expenses, prepare for seasonal cash-flow requirements, evaluate investments, manage debt, and make informed decisions about expansion.
There is no universal financial plan for every farm. A small family farm, livestock operation, large commercial farm, and mixed agricultural business can all have very different financial needs.
The most useful approach is one that reflects the farm's production cycle, financial commitments, available resources, and long-term goals.
In simple terms, better farm financial planning gives farmers a clearer view of today's finances while helping them prepare for tomorrow's growth.